
Why Choosing the Right Insurance Partner Matters

Home insurance brokers are licensed professionals who work on behalf of consumers to find and purchase home insurance from multiple insurance companies, unlike agents who represent specific insurers.
Quick Answer for Choosing Home Insurance Brokers:
- What They Do: Shop multiple insurance companies on your behalf to find the best coverage and rates
- Who They Represent: You, the homeowner (not the insurance company)
- Cost to You: Typically free—they’re paid commission by the insurance company you choose
- Best For: Homeowners seeking personalized guidance, multiple options, or coverage for unique/high-value properties
- How to Find One: Ask for referrals, verify state licensing, and check reviews and credentials
Your home is your biggest investment, and it deserves protection that fits your specific needs. But navigating the insurance landscape—with its dozens of companies and confusing policy terms—can be overwhelming. That’s where home insurance brokers come in. As licensed professionals, they act as your personal insurance shopper and advocate, working for you, not the insurance company. They compare options from multiple insurers, explain complex terms, and guide you to coverage that matches your situation.
Unlike captive agents (who work for one company) or even independent agents (who represent insurers), brokers represent your interests first. They’re paid by the insurance company you ultimately choose, so their service typically costs you nothing directly.
I’m Heidi Duncan, owner of Duncan & Associates Insurance Brokers, and I’ve spent my career helping homeowners steer the complexities of insurance by serving as their advocate and connecting them with the right coverage from multiple trusted carriers. In this guide, I’ll walk you through everything you need to know about working with home insurance brokers—from understanding what they do, to finding a reputable professional, to getting the most value from the relationship.
Must-know home insurance brokers terms:
- high value house insurance
- do i qualify for high net worth insurance
- how much umbrella insurance do i need high net worth
What is a Home Insurance Broker and How Do They Differ from an Agent?
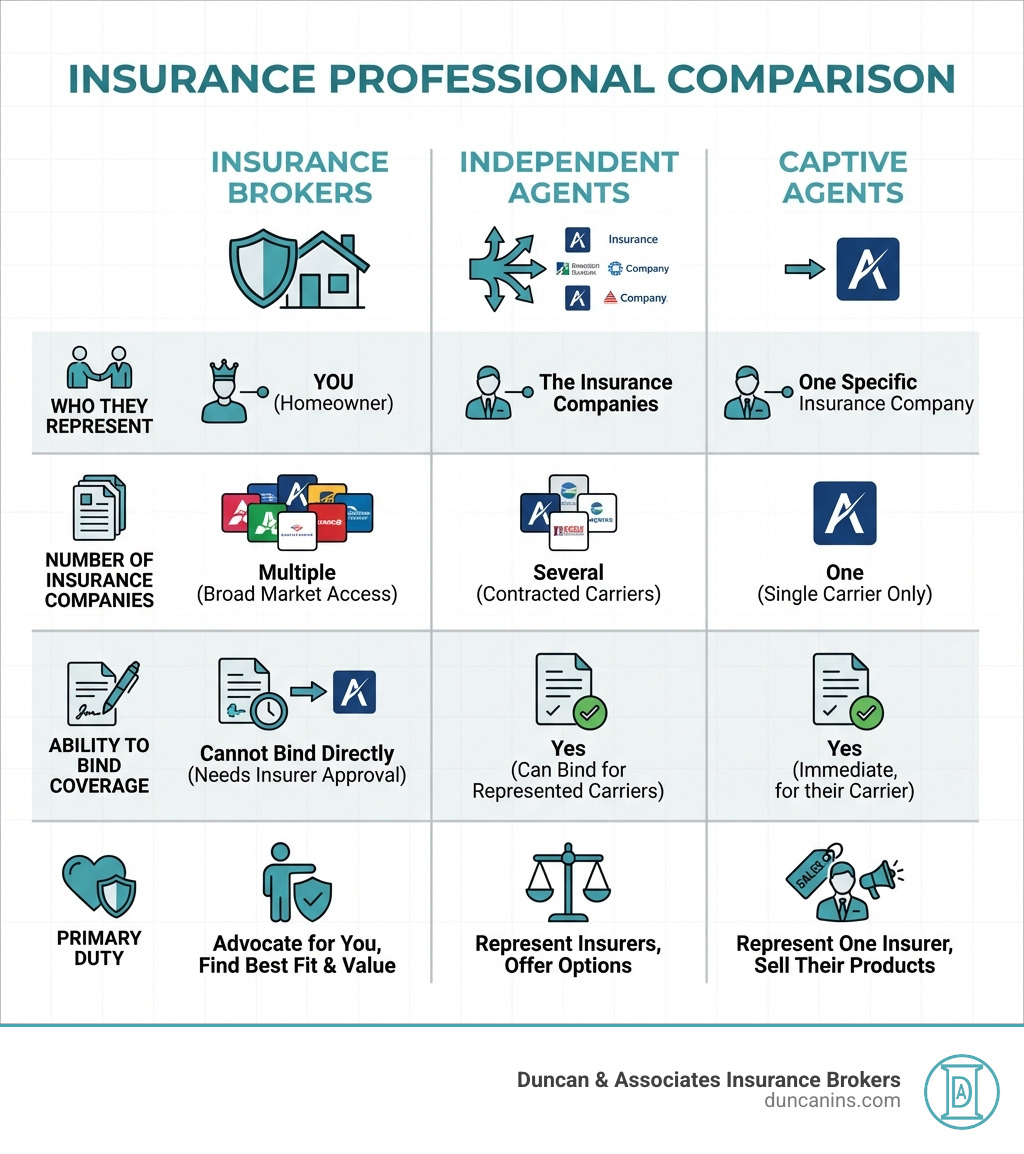
When looking to protect your home, you’ll encounter “insurance agent” and “home insurance broker.” While both are licensed professionals, their roles and loyalties are distinctly different.
A home insurance broker is an intermediary between you and various insurance companies. Our primary duty is to represent your interests, finding the best coverage and rates for your unique needs. We partner with multiple insurers, giving us the freedom to shop around on your behalf.
An insurance agent, on the other hand, represents insurance companies. Their main objective is to sell policies from the insurer(s) they work for. This is the most significant difference between the two roles.

Insurance agents typically fall into two categories:
- Captive Agents: These agents work exclusively for one insurance company and can only offer policies from that insurer. They are experts in their company’s products but cannot compare rates from competitors.
- Independent Agents: These agents have contracts with multiple insurers, offering a broader range of options than a captive agent. However, their loyalty is still primarily to the insurers they represent.
Here’s a quick overview of how these roles compare:
| Feature | Home Insurance Broker | Independent Agent | Captive Agent |
|---|---|---|---|
| Who They Represent | The consumer (You) | The insurance companies they contract with | One specific insurance company |
| Number of Carriers | Multiple (often a wider selection) | Multiple (within their contracted network) | One |
| Primary Duty | Finding the best coverage/rate for the client | Selling policies for their contracted insurers | Selling policies for their single insurer |
| Binding Authority | Typically submit applications; may require an agent to bind coverage | Can bind coverage directly | Can bind coverage directly |
Broker: Your Personal Insurance Shopper
As your personal insurance shopper, a broker is a dedicated advocate. Our core mission is client advocacy—we assess your unique situation to find the right protection. A key advantage is our access to multiple insurers, allowing us to shop the market for comprehensive coverage at a competitive price. Our advice is unbiased because our goal is to find a solution that satisfies you, building a long-term relationship. This client-first approach makes insurance easy and hassle-free. We also have specialized knowledge for unique properties, such as historic homes or estates, connecting you with insurers who handle High Value House Insurance or other niche needs.
Agent: The Insurer’s Representative
An agent’s primary role is to represent the insurance company.
- Captive Agents: Tied to one company, they are experts in its offerings but cannot provide alternatives from other carriers.
- Independent Agents: They work with several insurance companies, offering more options than captive agents, but their primary loyalty is to their contracted partners. Independent agents can typically “bind” coverage, officially putting a policy in place.
While agents provide value, especially for straightforward needs, a broker’s role is to cast a wider net to put your interests first. For More info about personal insurance, you can explore a range of offerings.
The Pros and Cons of Using Home Insurance Brokers
Choosing how to purchase home insurance is a significant decision. While working with home insurance brokers offers many benefits, it’s important to consider both sides to make an informed choice. Our goal is to provide a balanced perspective so you feel confident in your decisions.
Advantages of Partnering with a Broker
Working with a broker simplifies the insurance process and can lead to better outcomes:
- Expert Guidance: We break down complex policies and explain jargon, providing personalized insights so you understand what you’re buying.
- Time Savings: We do the legwork of comparing policies from multiple carriers, saving you hours of research.
- Access to More Options: Not being tied to one insurer means we can compare policies from a wide array of companies, increasing your chances of finding the perfect fit.
- Potentially Better Rates: We leverage competition among insurers to find competitive rates, often uncovering savings through bundling or specific policy features.
- Help with Complex Situations: We excel at finding solutions for unique properties, high-risk areas, or complex claims histories, which is especially valuable for High Value House Insurance.
- Claims Assistance and Advocacy: If you file a claim, we act as your advocate, guiding you through the process and helping resolve disputes.
- Ongoing Client Service: Our relationship continues after the sale. We’re available for policy changes, renewals, and questions, acting as your trusted advisor.
For More info about our insurance quote process, you can see how we streamline getting you the best options.
Potential Disadvantages to Consider
While the advantages are significant, it’s important to be aware of potential drawbacks:
- No Access to All Insurers: Some companies only sell directly to consumers or through captive agents, bypassing brokers. However, we partner with a vast network, so this rarely impacts our ability to find excellent coverage.
- Potential for Commission Influence: Since brokers are paid by the insurer, there’s a theoretical concern we might favor higher-commission policies. Reputable brokers, however, prioritize long-term client relationships and satisfaction over short-term gains.
- Broker Fees (Rare): In rare cases, a broker may charge a fee for their services, which must be disclosed upfront. This is not common for standard home insurance, and we believe in full transparency.
- Possible Online-Only Discounts Missed: Some insurers offer discounts for buying directly online. While we strive to find the best rates, the comprehensive advice and custom coverage we provide often result in greater overall value.
Navigating the Insurance Process with a Broker
Partnering with a home insurance broker is designed to make your insurance journey smoother and more efficient. We aim to take the stress out of finding the right coverage, allowing you to focus on what matters most – your home and family. Let’s walk through what you can expect when you work with us.
Preparing for Your Consultation
To find you the most accurate and competitive quotes, we’ll need some information about you and your home. The more details you provide, the better we can tailor your options.
Here’s what we’ll typically need:
- Property Details: The age of your home, its construction type (e.g., brick, wood frame), square footage, and any recent renovations. We’ll also ask about the age of key systems like the roof, plumbing, and electrical.
- Personal Information: Your name, contact details, and sometimes your credit score (which can influence premiums in many states).
- Claims History: Details of any previous home insurance claims. We generally recommend saving your policy for major events and paying for minor damages out-of-pocket to keep future premiums down.
- Valuables Inventory: A list of high-value items like jewelry, art, or collectibles. Standard policies have limits on these items, so we can discuss riders to ensure they are adequately protected.
For a deeper dive, check out our Homeowners Insurance WA Complete Guide.
Understanding Coverage Levels and Deductibles
One of our primary roles is to explain policy language and help you understand your coverage options. We’ll guide you through the Homeowners Insurance Basics, including standard coverage types like Dwelling, Personal Property, and Liability.
We’ll also explain the difference between Replacement Cost (pays to rebuild or replace without deducting for depreciation) and Actual Cash Value (factors in depreciation). While actual cash value policies have lower premiums, most homeowners prefer replacement cost for greater financial security.
Then there are deductibles—the amount you pay out of pocket before insurance kicks in. A higher deductible typically means a lower premium. We’ll help you find a deductible that balances affordability with your comfort level for out-of-pocket expenses, often suggesting at least $1,000 to save on premiums.
Beyond standard coverage, we can help you explore special coverages for risks specific to our region, such as Earthquake Insurance or Flood Insurance. We can also provide expert guidance on specialized policies like Mobile Home Insurance.
Post-Purchase Support: Claims and Policy Changes
Our partnership doesn’t end once your policy is in place. We’re here for you every step of the way. While insurance companies process claims, we act as your advocate, helping you understand what’s covered and resolving any issues that arise. Your life is dynamic, so we also assist with policy reviews and adjustments as your needs change, ensuring your coverage evolves with you. This ongoing client service is a cornerstone of what we do, making insurance easy and hassle-free for the long term.
Finding and Verifying a Reputable Broker
Choosing the right home insurance broker is about more than just finding a good deal; it’s about building a relationship with a trusted advisor. You want someone with expertise, integrity, and a genuine commitment to your best interests. Performing due diligence is key to ensuring you partner with a reputable professional.
How to Find Reputable Home Insurance Brokers
Finding a great broker often starts with trusted sources. Here are some strategies we recommend:
- Referrals: Ask friends, family, or your real estate agent for recommendations. Personal referrals often lead to brokers who have a proven track record of excellent service.
- Online Research: Use search engines and review sites like Yelp or the Better Business Bureau (BBB) to find brokers in your area. Pay attention to reviews and ratings, looking for consistent praise regarding customer service, expertise, and responsiveness.
- Professional Organizations: Many brokers are members of professional associations, which often uphold ethical standards and provide resources for finding qualified professionals.
- Website and Online Presence: A reputable broker will have a clear, informative website that explains their services and philosophy. Look for signs of transparency and a client-first approach.
Verifying Credentials and Licensing
Once you have a few potential home insurance brokers in mind, the next crucial step is to verify their credentials and ensure they are properly licensed. This protects you and confirms their legitimacy and adherence to industry standards.
- State Licensing Requirements: Insurance agents and brokers are licensed by the states they operate in. This typically requires them to complete specific pre-licensing courses, pass comprehensive exams, and fulfill continuing education requirements to maintain their license.
- Using Regulatory Databases: The most reliable way to verify a broker’s license is through your state’s Department of Insurance website. You can also use the National Association of Insurance Commissioners (NAIC) website, which often provides links to state regulatory bodies where you can look up individual licenses. This allows you to confirm that a broker is currently licensed and check for any disciplinary actions.
- Background Checks: While you might not conduct a formal background check, looking up a broker’s history through state licensing boards or the BBB can provide insights into their professional standing.
Verifying these details ensures you’re working with a legitimate and qualified professional, giving you peace of mind throughout your insurance journey.
Frequently Asked Questions about Home Insurance Brokers
We understand that you might have more questions about how home insurance brokers operate and how they can benefit you. Here, we address some of the most common inquiries we receive.
How are home insurance brokers compensated?
This is a very common and important question, and we believe in complete transparency. Home insurance brokers are typically compensated through a commission-based model. This means we receive a commission directly from the insurance company when you purchase a policy through us. This commission is usually a percentage of the insurance premium.
What’s crucial to understand is that this compensation model means:
- No Direct Cost to the Homeowner: For you, the homeowner, our service is typically free. You don’t pay us a separate fee out of your pocket. The cost of the commission is already factored into the premium set by the insurance company, regardless of whether you go through a broker or buy directly.
- Paid by the Insurer: The commission comes from the insurer’s marketing and distribution budget, not as an added charge to your premium.
- Transparency in Fees: In rare instances where a broker might charge an additional fee, they are legally required to disclose this to you upfront. We pride ourselves on making insurance 100% hassle-free, which includes being transparent about all aspects of our service.
This compensation structure allows us to offer you unbiased advice and shop multiple carriers without you incurring additional costs. Our goal is to find you the best policy, knowing that a happy, well-protected client is our best asset.
When should you use a home insurance broker?
While everyone can benefit from the expertise of a home insurance broker, certain situations make our services particularly valuable:
- Complex Needs: If your insurance needs are anything but standard, we are an invaluable resource. This includes owning unique properties, having a high-value home, or requiring specialized coverage.
- High-Value Homes: For properties that fall into the high-net-worth category, standard policies often don’t provide adequate protection. We specialize in finding comprehensive high value house insurance solutions that cater to the unique risks and asset levels associated with luxury properties.
- Unique Properties: Whether you own a historic home, a custom-built residence, or even require Mobile Home Insurance, we can steer the market to find insurers willing to cover properties that might be considered “unusual” by standard carriers.
- Lack of Time or Expertise: If you simply don’t have the time to research dozens of policies, compare quotes, and understand complex terms, we handle all that legwork for you. Our expertise ensures you get the right coverage without the headache.
- First-Time Homebuyers: The process of buying a home is already overwhelming. Adding insurance to the mix can be daunting. We can guide first-time homebuyers through the requirements, helping them understand their options and secure the necessary coverage for their mortgage.
- Seeking the Best Value: If your primary goal is to ensure you’re getting the most comprehensive coverage for the most competitive price, our ability to shop multiple carriers is a significant advantage.
Is it more expensive to use a broker?
No, typically it is not more expensive to use a home insurance broker, and often, it can lead to savings.
Here’s why:
- Rates Are Set by Insurers: The insurance premiums you pay are set by the insurance companies themselves. These rates don’t change simply because you’re working with a broker. The commission we receive is already built into the insurer’s pricing model.
- Brokers Can Find Competitive Pricing: Our ability to shop around among numerous insurance providers means we can compare various quotes and coverage options. This often leads to us finding you a policy that offers better value or a lower premium than you might find on your own. We can uncover discounts you weren’t aware of or identify insurers who are more competitive for your specific risk profile.
- Potential for Savings Outweighs Any Rare Fees: While, in very rare circumstances, a broker might charge a fee, the potential savings we can achieve by finding you a more suitable and affordable policy typically far outweigh any such fees. Plus, as a client-first agency, we prioritize transparency, meaning any fees would be discussed upfront.
- Value Beyond Price: Beyond just the premium, consider the value of expert advice, personalized service, advocacy during claims, and the peace of mind knowing you have the right coverage. These benefits often make working with a broker a more cost-effective choice in the long run, even if the premium itself were identical to a direct quote.
Your Partner in Protection
Your home is more than just a structure; it’s where memories are made, families grow, and your most cherished possessions reside. Protecting this significant investment with the right home insurance is not just a necessity, but a declaration of care for your future.
At Duncan & Associates Insurance Brokers, we are dedicated to being your trusted partner in this essential endeavor. We embody the true spirit of home insurance brokers by placing your needs at the forefront. Our commitment is to empower you, the homeowner, by providing clarity, choice, and unwavering support in the often-complex world of insurance. We make insurance easy and 100% hassle-free, ensuring you receive expert, client-first service every step of the way.
We believe that finding the right insurance shouldn’t be a chore, but an empowering experience. Whether you’re a first-time homebuyer, a seasoned homeowner, or someone with unique and high-value property considerations, we are here to simplify the process, explain the jargon, and secure the comprehensive protection you deserve.
Ready to experience the Duncan & Associates difference? We invite you to explore how our client-first approach can benefit you. Learn more about our high-net-worth insurance solutions or simply reach out to us for a personalized consultation. Let us be the guardian of your home, so you can focus on making it a haven.
